

Best Business Credit Cards for Small Business in 2026

Eneba Hub contains affiliate links, which means we may earn a small commission if you make a purchase through them—at no extra cost to you. Learn more

Chase Ink Business Unlimited leads the best business credit cards for small business right now: $0 annual fee, unlimited 1.5% cash back, a $1,000 bonus, no categories to track. It beats American Express Blue Business Cash, Chase Ink Business Cash, Capital One Spark Cash Plus, and American Express Blue Business Plus on effort-to-reward balance, making it the best small business credit card to start with if you want a no annual fee business credit card.
Every figure below came from each issuer’s own page, with sole-proprietor eligibility confirmed on Chase‘s and Capital One‘s guidance. This list of the best business credit cards for small business reflects live terms, so confirm details before applying.
Jump to:
What Is a Small Business Credit Card?
A small business credit card is a card issued in your business’s name, kept separate from your personal spending. It’s built to earn business credit card rewards on everyday purchases while helping you establish credit history for the business itself. Most business cards still require a personal guarantee, so you’re on the hook personally if the business can’t pay, along with a hard inquiry at application.
You don’t need a formal LLC or EIN to apply. Sole proprietors and freelancers can usually use their own Social Security number instead, which is why even the most ambitious side hustles can qualify, and why the best business credit cards for small business remain within reach for owners just starting out.
A credit card can handle everyday business spending, while one of the best business savings accounts for small business can be a better place for cash reserves you don’t need right away.
Best Business Credit Cards for Small Business: The Top 5 Compared
Here is how the top five business credit cards for small business compare at a glance. Each row shows the annual fee, the welcome bonus, and who the card suits best, so you can shortlist fast and jump to the full review below.
| Rank | Card | Best For | Annual Fee | Welcome Bonus |
|---|---|---|---|---|
| 1 | Chase Ink Business Unlimited | Simple uncapped 1.5% | $0 | $1,000 ($8,000 spend) |
| 2 | Amex Blue Business Cash | Flat 2% under $50k/year | $0 | $250 ($3,000 spend) |
| 3 | Chase Ink Business Cash | Bonus categories | $0 | $1,000 ($8,000 spend) |
| 4 | Capital One Spark Cash Plus | High spend, biggest bonus | $150 | $2,000+ ($30,000 spend) |
| 5 | Amex Blue Business Plus | Flexible points, not cash | $0 | 15,000 points ($3,000 spend) |
Among the best business credit cards for small business, the two Chase Ink cards share the same $1,000 bonus after $8,000 in four months and identical APR terms, but use different rewards structures. Capital One Spark Cash Plus carries the highest spend requirement and the only annual fee here, but also the largest total bonus potential on this list.
For a business credit card for startup founders, the two no annual fee cards up top are the more forgiving pick. Whichever you choose, all three rank among the best small business credit card options we’d recommend today.
The Best Business Credit Cards for Small Business, Reviewed
Below is the full breakdown of each card, with the verified fee, APR, rewards, and who it fits. The set splits into flat-rate simplicity, bonus categories, and one high-spend charge card. Start with our top pick, Chase Ink Business Unlimited.
1. Chase Ink Business Unlimited® Credit Card: Best Overall
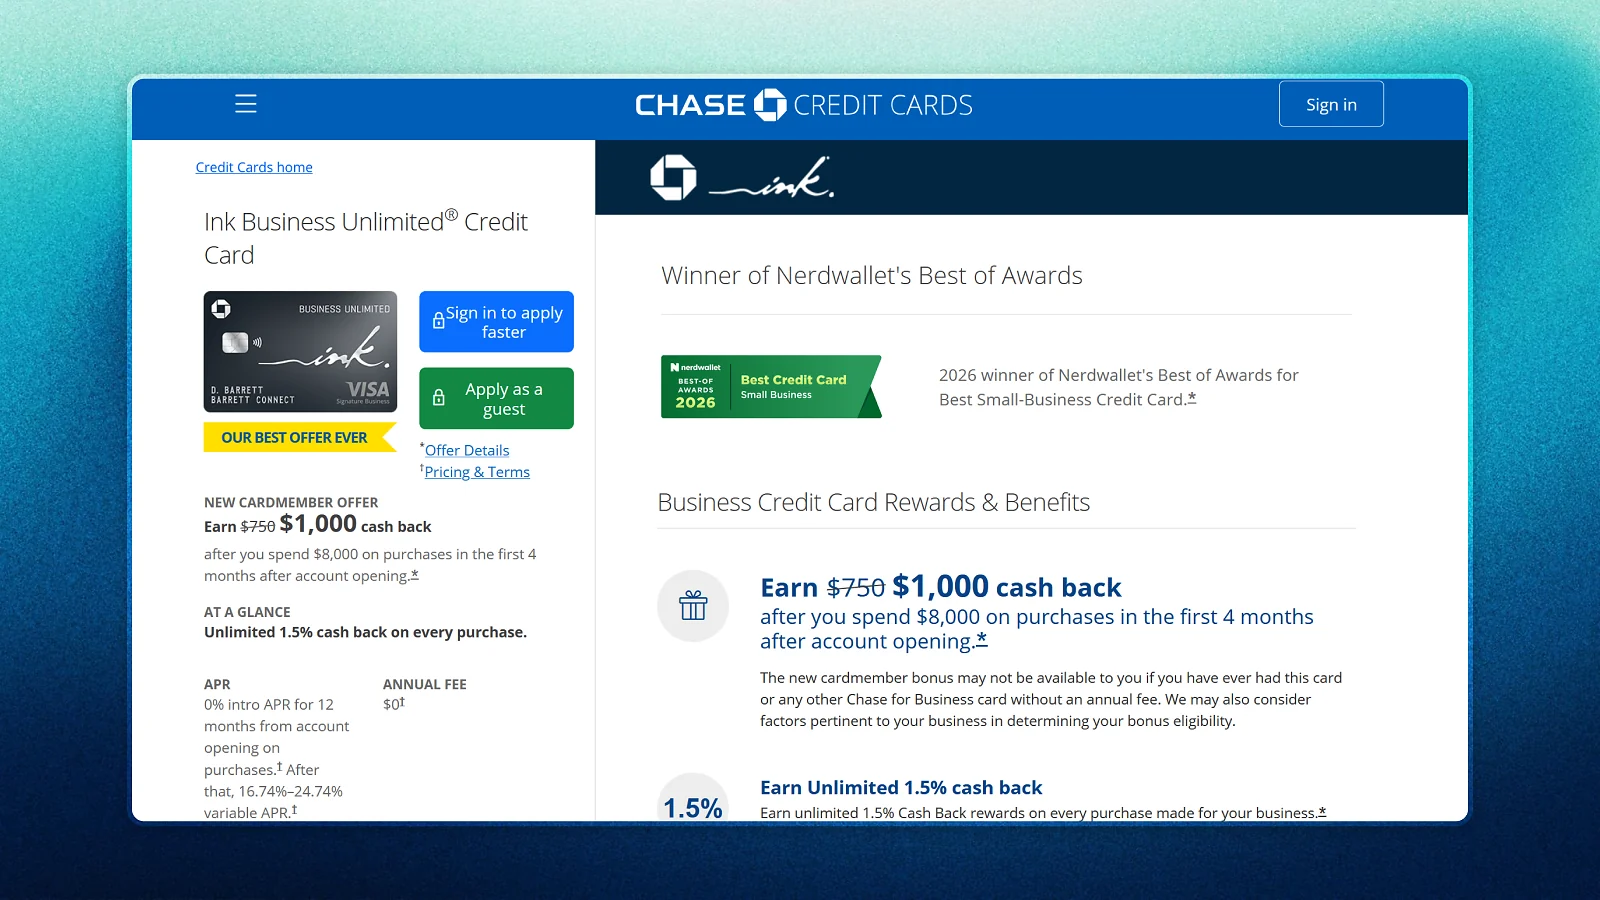
The Chase Ink Business Unlimited Credit Card is the best small business credit card overall, pairing NerdWallet’s 2026 Best Small-Business Credit Card award with unlimited 1.5% cash back and zero categories to track. Among the best business credit cards for small business, it stands out for owners who want simple, predictable rewards without having to manage rotating or spending-specific categories.
| Card Feature | Details |
|---|---|
| Annual fee | $0 |
| APR | 0% intro for 12 months, then 16.74% to 24.74% variable |
| Rewards | Unlimited 1.5% cash back on everything |
| Welcome bonus | $1,000 after $8,000 spend in 4 months |
| Credit needed | Good to excellent |
| Best for | Simple, uncapped flat rate |
Ink Business Unlimited keeps things effortless: a flat, uncapped 1.5% cash back on every purchase, no categories, no annual cap. There’s no annual fee, a 0% intro APR for 12 months, then 16.74%–24.74% variable, and a $1,000 bonus after $8,000 spent in four months. That’s Chase’s best-ever public offer on this card, up from the usual $750, so confirm it’s still live before applying. NerdWallet named this the best business credit card for small business in its 2026 Best-of Awards, hosted on Chase’s own page.
On eligibility, this is a card sole proprietor owners can open with a Social Security number instead of an EIN, per Chase’s guidance. Expect a personal guarantee and a hard inquiry at application, though ongoing activity typically reports only to business bureaus unless the account goes seriously delinquent.
Among the best business credit cards for small business, it’s the simplest no annual fee option to get approved for, with uncapped rewards and nothing to activate.
See our head-to-head comparison of Chase Ink Business Unlimited and American Express Blue Business Cash, two of the best business credit cards for small business.
2. American Express Blue Business Cash™ Card: Best Flat Rate Under $50k/Year
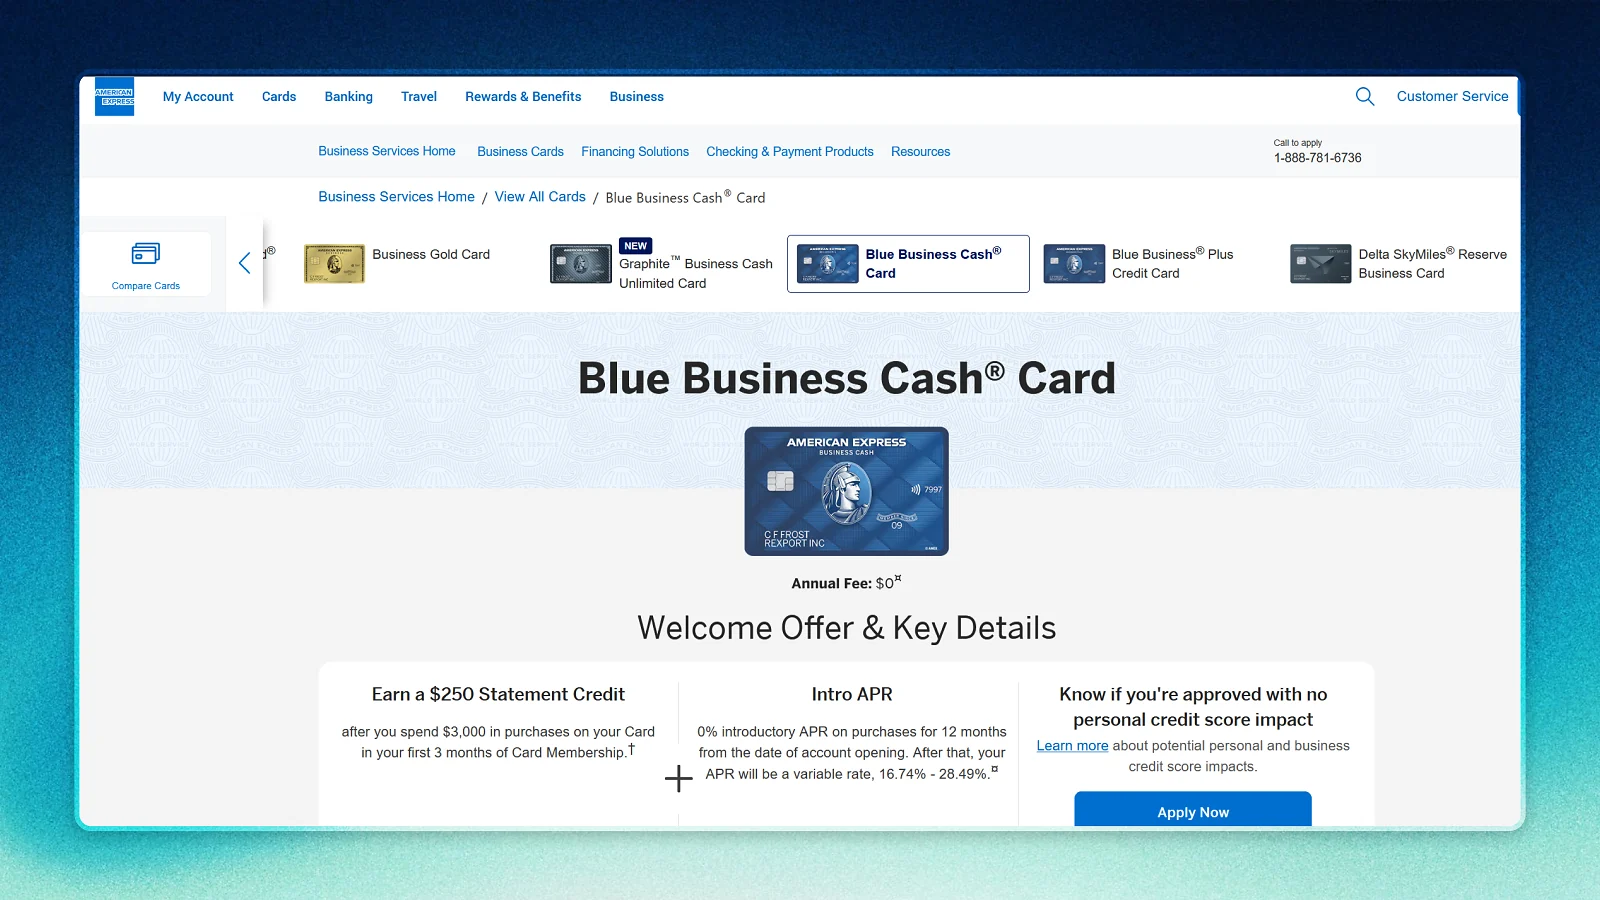
American Express Blue Business Cash takes second place in our ranking of the best business credit cards for small business, thanks largely to its strong flat cash-back structure. It’s the best small business credit card here for businesses that spend under $50,000 a year, earning 2% cash back on the first $50,000 in eligible purchases each calendar year, then 1%.
| Card Feature | Details |
|---|---|
| Annual fee | $0 |
| APR | 0% intro for 12 months, then 16.74% to 28.49% variable |
| Rewards | 2% on the first $50,000/year, then 1% |
| Welcome bonus | $250 after $3,000 spend in 3 months |
| Credit needed | Good to excellent |
| Best for | Flat 2% under $50k annual spend |
Blue Business Cash pays 2% cash back automatically on the first $50,000 of eligible purchases each calendar year, then 1% after that, out-earning a flat 1.5% card as long as annual spend stays under that cap. There’s no annual fee, a 0% intro APR for 12 months, then a 16.74% to 28.49% variable rate, and a $250 statement credit after $3,000 of spend in three months. Expanded Buying Power lets you spend above your credit limit when you qualify, useful for a business credit card for startup owners with lumpy monthly bills.
Amex offers a no-impact pre-qualification check, but the real application triggers a hard inquiry and a personal guarantee. It’s another card business credit card sole proprietor applicants and single-member LLCs can generally get with an SSN, and it reports to business bureaus for normal activity. As a no annual fee business credit card with the strongest flat rate here, it’s a solid pick among the best business credit cards for small business owners whose spend stays modest.
If cash back is your main priority and you don’t specifically need a business card, you can also compare the best credit cards for cashback.
For a closer look at two of the best business credit cards for small business, compare American Express Blue Business Cash vs. Chase Ink Business Unlimited below.
3. Chase Ink Business Cash® Credit Card: Best Bonus Categories
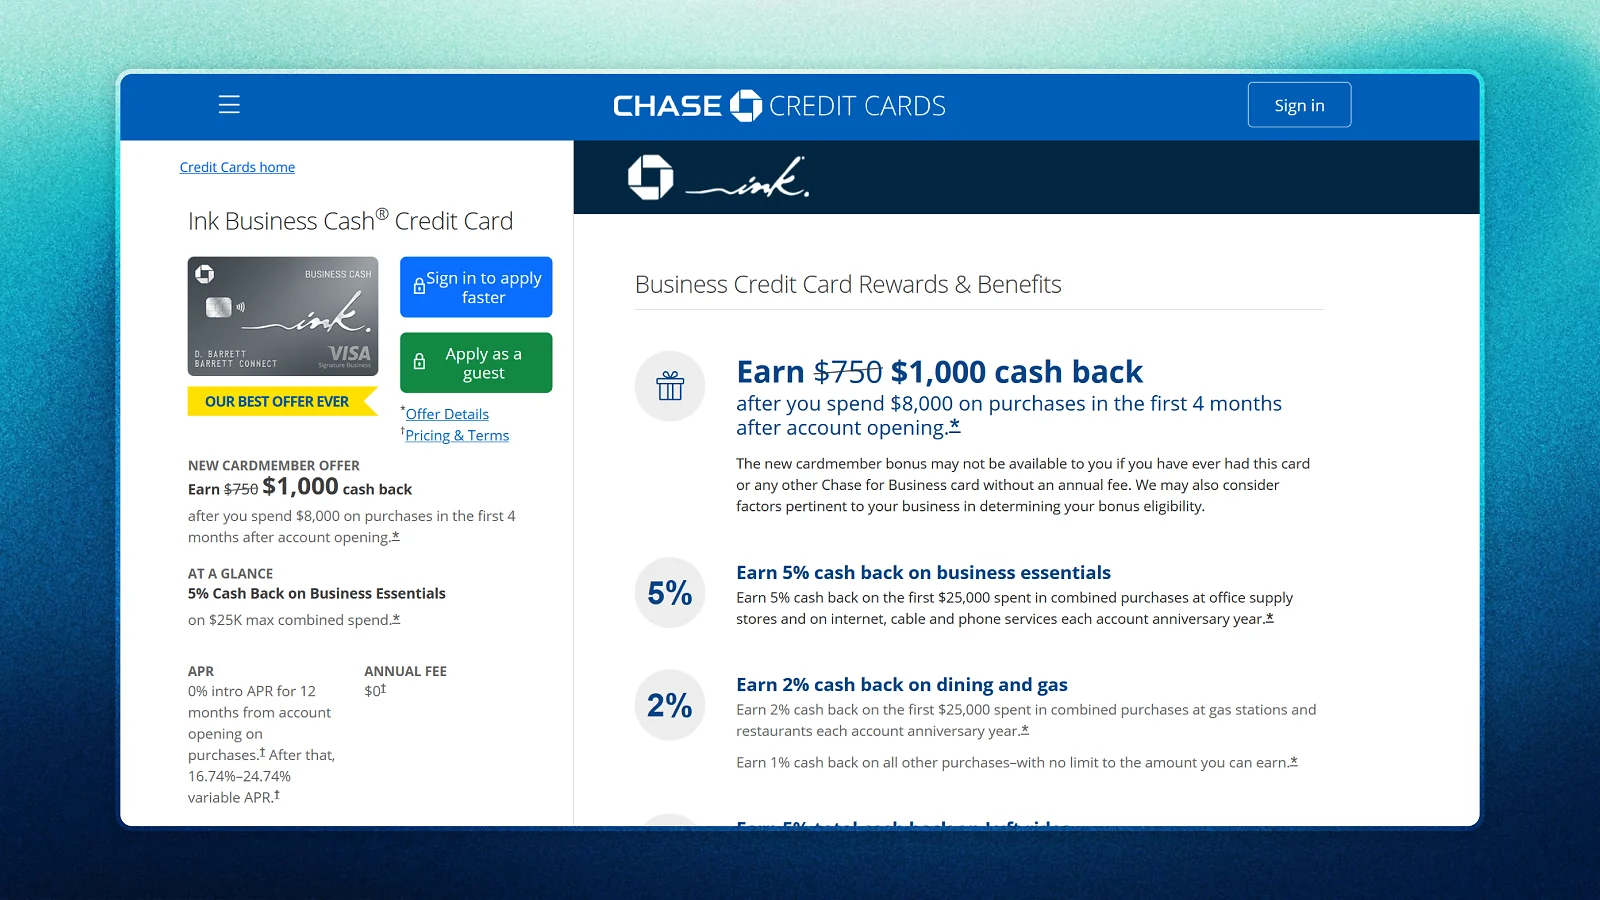
Chase Ink Business Cash ranks third on our list of the best business credit cards for small business and stands out as the best small business credit card for owners whose expenses fall into its bonus categories. If you spend steadily on office supplies, internet, phone services, gas, or dining, its higher category rates can outperform a simpler flat-rate card.
| Card Feature | Details |
|---|---|
| Annual fee | $0 |
| APR | 0% intro for 12 months, then 16.74% to 24.74% variable |
| Rewards | 5% and 2% categories (capped), 1% base |
| Welcome bonus | $1,000 after $8,000 spend in 4 months |
| Credit needed | Good to excellent |
| Best for | Category-based rewards |
Ink Business Cash is the category sibling to Ink Business Unlimited. It pays 5% cash back on the first $25,000 spent in combined purchases at office supply stores and on internet, cable, and phone services each account anniversary year, 2% on the first $25,000 combined at gas stations and restaurants each account anniversary year, and 1% on everything else with no cap.
The fee, APR, and $1,000 welcome bonus are identical to Ink Business Unlimited, since both cards share the same terms. That makes it a rare no annual fee business credit card that can beat a flat 2% card on the right spending mix.
Eligibility matches Ink Business Unlimited exactly: this is a business credit card sole proprietor owners can use with an SSN instead of an EIN, a personal guarantee and hard inquiry apply at application, and ongoing reporting goes to business bureaus unless the account falls seriously behind. If your monthly bills lean heavily on those bonus categories, it is one of the best business credit cards for small business owners chasing category-based business credit card rewards.
4. Capital One Spark Cash Plus: Best for High Spend and the Biggest Bonus
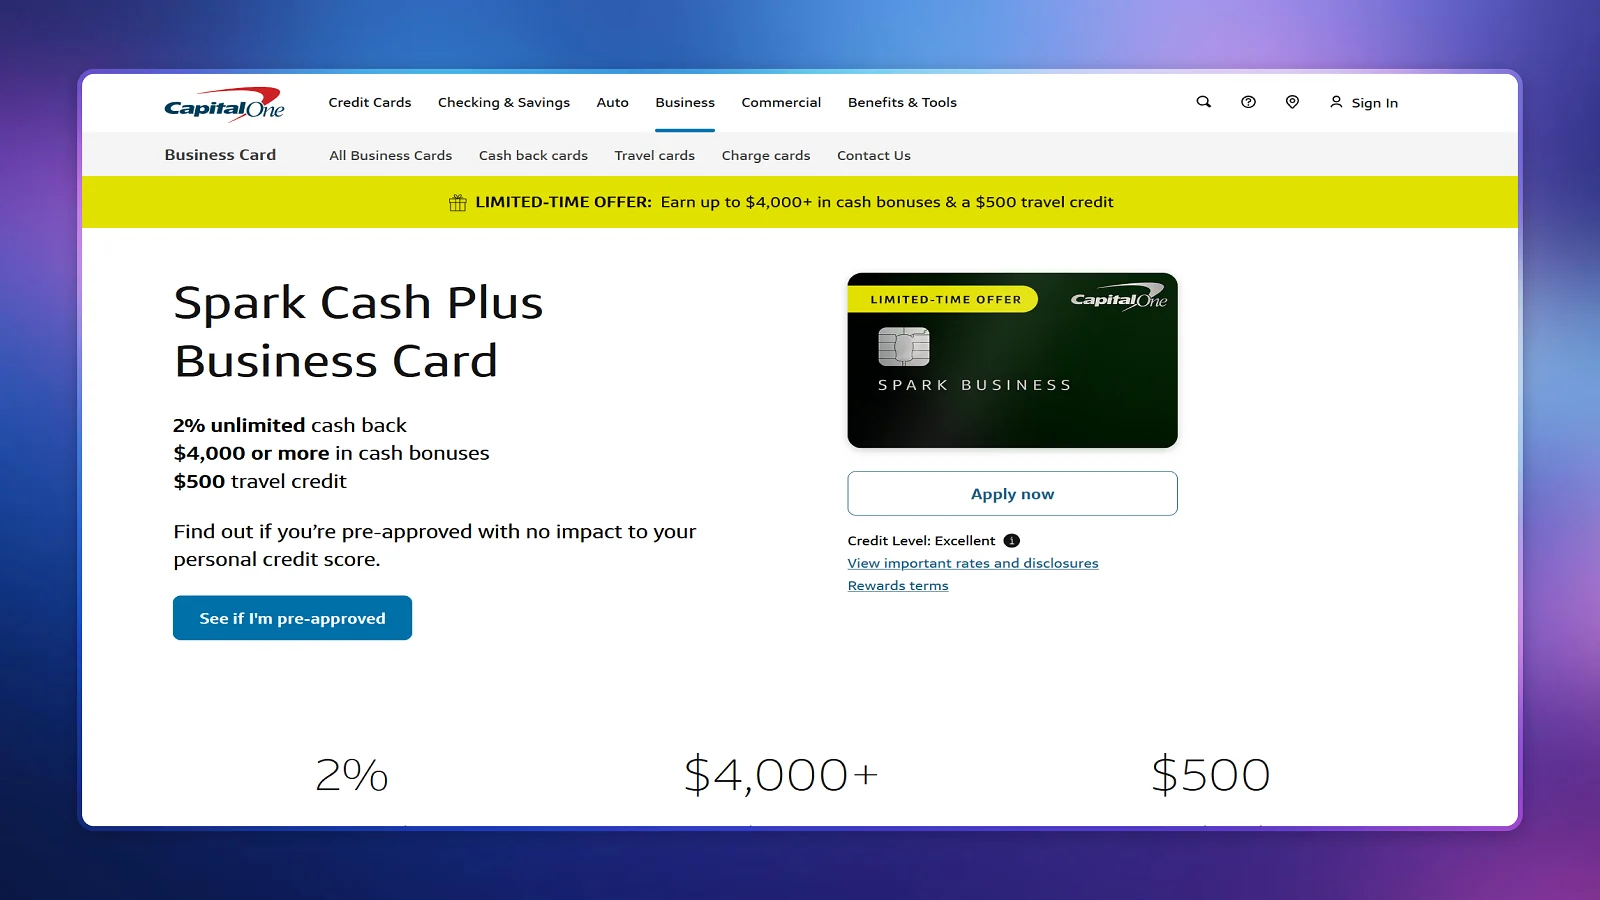
Capital One Spark Cash Plus is the best small business credit card for high-spending businesses that can pay in full and want the largest bonus of the five, on a card with no preset spending limit.
| Card Feature | Details |
|---|---|
| Annual fee | $150 (refunded at $150,000/year spend) |
| Card type | Charge card, no preset limit, pay in full |
| Rewards | Unlimited 2% cash back, 5% on Capital One travel |
| Welcome bonus | $2,000 after $30,000 spend in 3 months (repeatable), plus a $500 travel credit |
| Credit needed | Excellent (stated on-page) |
| Best for | High-spend businesses |
Spark Cash Plus is the outlier here, and the most rewarding for the right business. It is a charge card with no preset spending limit, designed to be paid in full, and it pays an unlimited flat 2% cash back on everything, plus 5% on hotels, vacation rentals, and rental cars booked through Capital One Business Travel.
The bonus is the biggest in this set: $2,000 after $30,000 of spend in three months, repeatable at $2,000 for every additional $500,000 spent in year one, plus a $500 travel credit at the same threshold. It is the only card here with an annual fee, $150, though Capital One refunds it every year you spend $150,000 or more.
It is also the only card that states its credit tier on-page, Excellent, making it the least accessible of the five for a newer business. Capital One’s own guidance confirms this is a business credit card sole proprietor owners can open with an SSN. The card is designed to be paid in full, but it does offer a Pay Over Time option for part of your balance, with a variable APR of about 25.74%, per Capital One’s current terms.
If you specifically want a business credit card no personal guarantee, this is not it, since a guarantee applies here just as it does on every other card in this list. For a high-volume company, though, it offers the strongest business credit card rewards of the five.
5. American Express Blue Business Plus® Credit Card: Best for Flexible Points
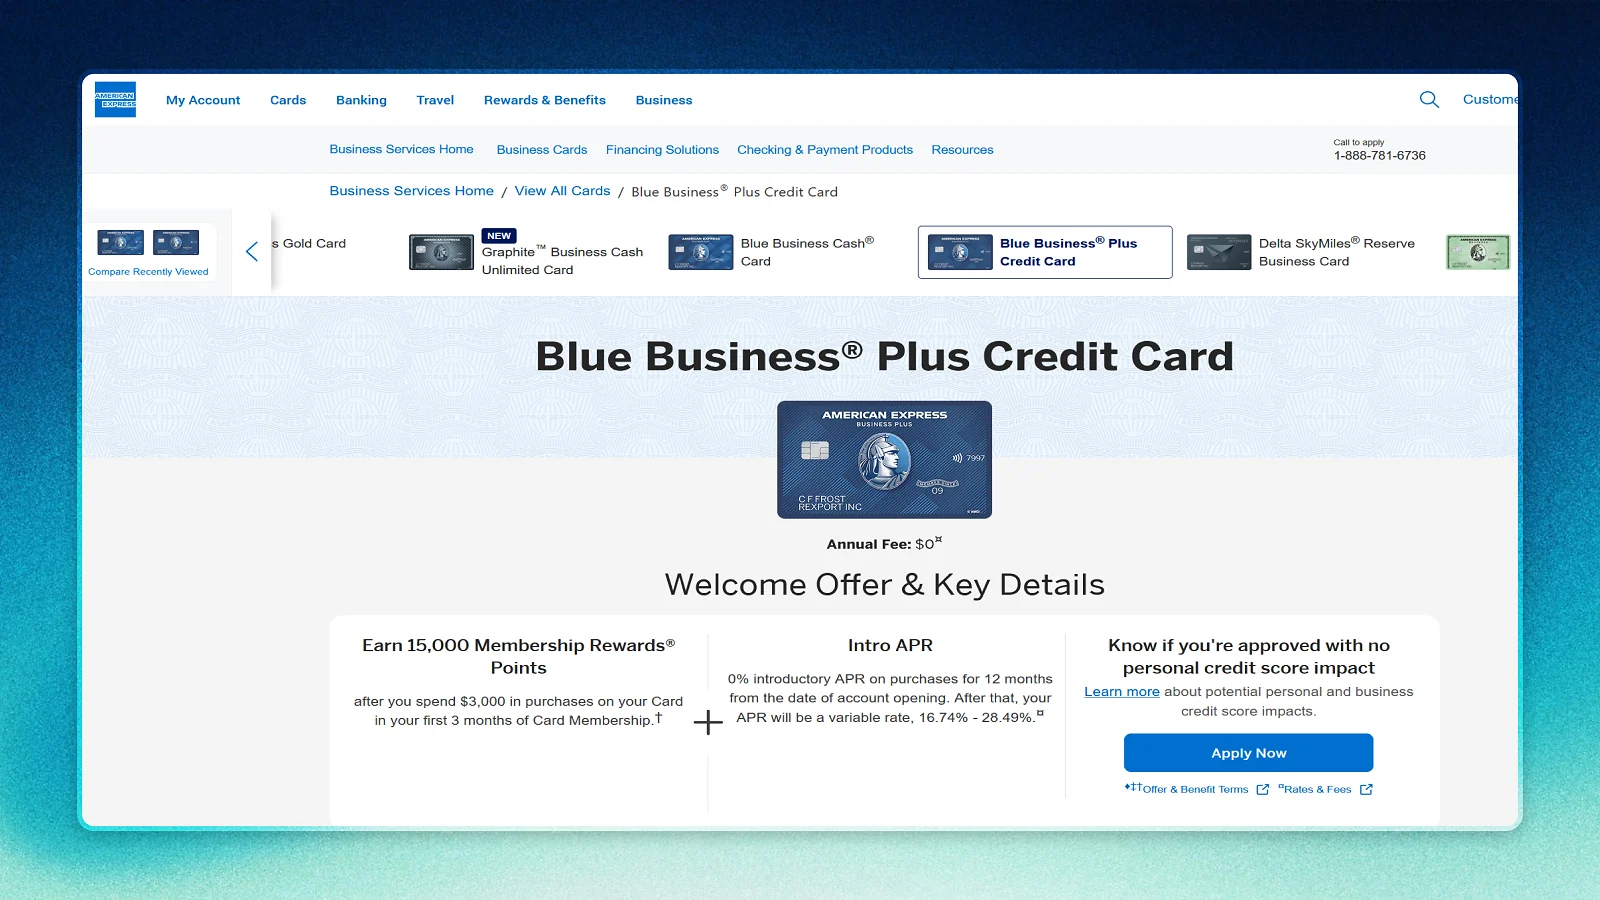
American Express Blue Business Plus is the best small business credit card for owners who would rather earn flexible Membership Rewards points than a straight cash statement credit.
| Card Feature | Details |
|---|---|
| Annual fee | $0 (including employee cards) |
| APR | 0% intro for 12 months, then 16.74% to 28.49% variable |
| Rewards | 2X points on the first $50,000/year, then 1X |
| Welcome bonus | 15,000 points after $3,000 spend in 3 months |
| Credit needed | Good to excellent |
| Best for | Flexible Membership Rewards points |
Blue Business Plus is the points-earning twin of Blue Business Cash. It earns 2X Membership Rewards points on the first $50,000 of eligible purchases each year, then 1X, and comes with a 15,000-point welcome bonus after $3,000 of spend in three months.
The fee and APR match Blue Business Cash: no annual fee, even on employee cards, a 0% intro APR for 12 months, then 16.74% to 28.49% variable, since both cards share the same Amex business agreement. That combination of a no annual fee business credit card and transferable points is unusual at this tier.
The only real difference is what you earn. Membership Rewards points can be redeemed for travel, gift cards, or transferred to Amex’s airline and hotel partners, where their value can exceed a flat cash rate, so this is the pick if you value flexibility over simplicity. Eligibility and reporting match Blue Business Cash: it is a business credit card sole proprietor applicants can get with an SSN, and a personal guarantee and hard inquiry apply at application. For a business credit card for startup owners who travel often, the points can beat cash outright, which is why it earns a spot among the best business credit cards for small business.
Chase Ink Business Unlimited vs. American Express Blue Business Cash
These are the two top flat-rate cards here, so they make the most useful head-to-head.
On ongoing rewards, American Express Blue Business Cash actually wins for most small businesses, since its 2% rate beats Chase Ink Business Unlimited’s 1.5% right up until annual spend passes $100,000. That’s the real crossover point, not $50,000: Blue Business Cash earns 2% on the first $50,000 and 1% after, while Ink Business Unlimited earns 1.5% with no cap. At $100,000 a year both return $1,500; below that, Blue Business Cash earns more, and only past it does Ink Business Unlimited pull ahead.
So why does Ink Business Unlimited still top the list of best business credit cards for small business? Because business credit card rewards aren’t the only factor. It carries NerdWallet’s 2026 Best Small-Business Credit Card award and a far larger $1,000 welcome bonus, versus $250 on Blue Business Cash, which swings first-year value hard in Chase’s favor for anyone who can meet the $8,000 spend. For a lower-spend business that would never approach that threshold, Blue Business Cash is the better small business credit card.
| Feature | Chase Ink Business Unlimited | Amex Blue Business Cash |
|---|---|---|
| Rewards | Unlimited 1.5% | 2% up to $50,000/year, then 1% |
| Annual cap | None | $50,000 for the 2% rate |
| Welcome bonus | $1,000 ($8,000 spend) | $250 ($3,000 spend) |
| Award | 2026 NerdWallet Best Small-Business Card | None on-page |
| Intro APR | 0% for 12 months | 0% for 12 months |
Among the best business credit cards for small business, Blue Business Cash is a strong pick if you spend under $100,000 a year, while Ink Business Unlimited may be the best small business credit card for higher spend and a bigger bonus.
Editor’s Pick
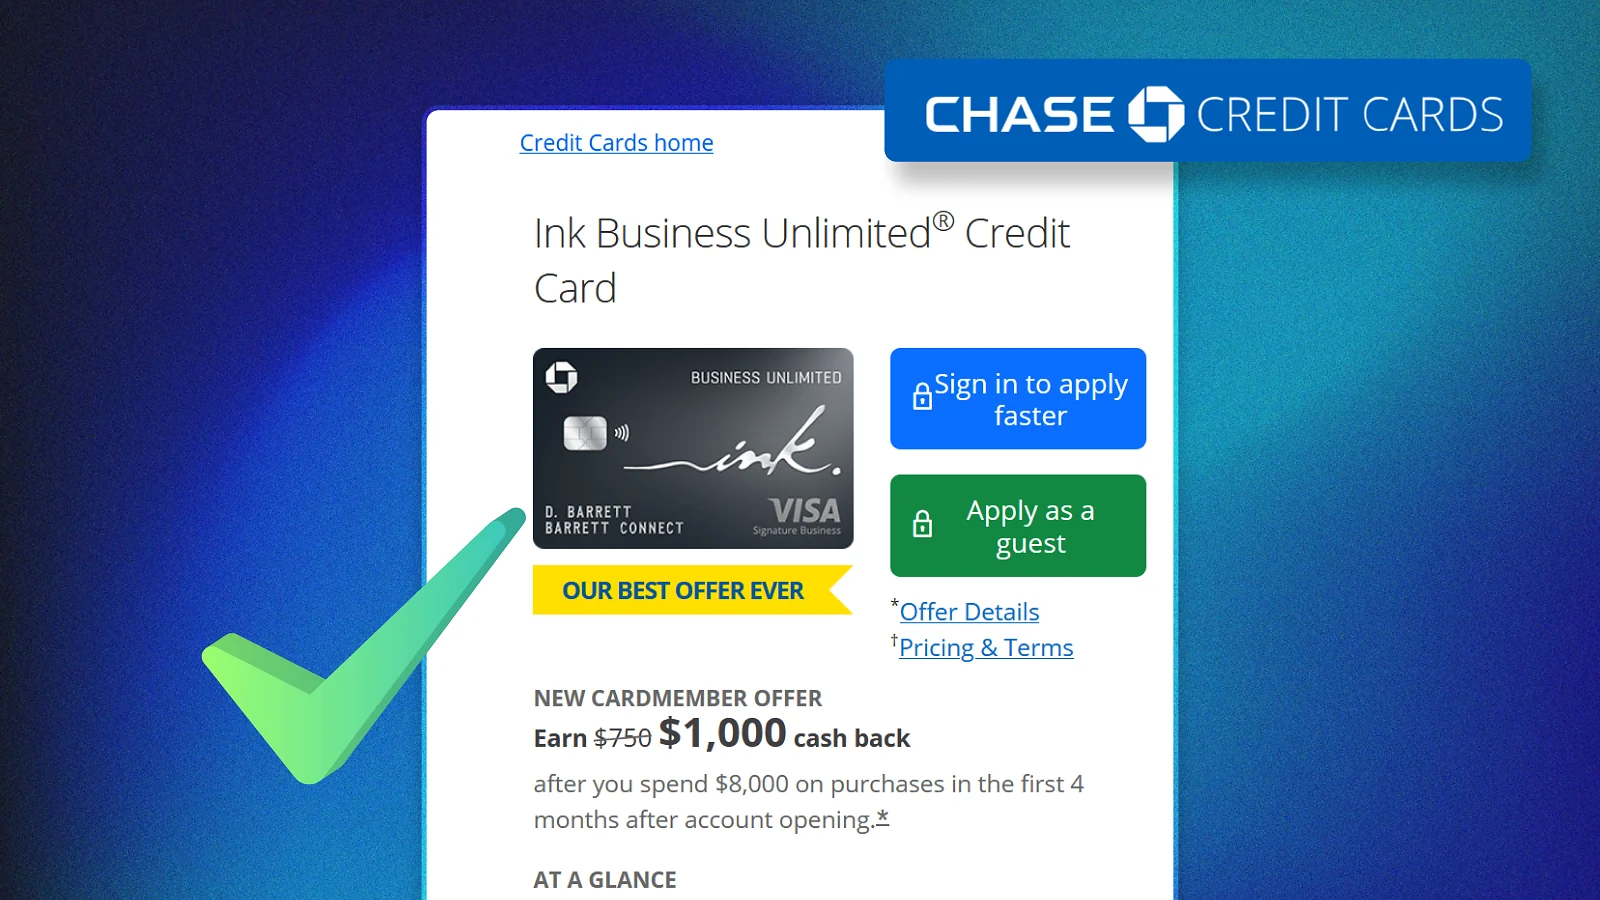
Editor’s Pick: Chase Ink Business Unlimited® Credit Card. Chosen for NerdWallet’s 2026 Best Small-Business Credit Card award, a $0 annual fee, and unlimited 1.5% cash back with zero categories to activate. No admin, no categories to track, just straightforward business credit card rewards on everything you spend. That simplicity is exactly why it sits among the best business credit cards for small business.
Skip it only if your annual spend is under $100,000 and you’d rather earn a higher everyday rate, where American Express Blue Business Cash at 2% is the better small business credit card.
How Much Can Your Business Earn on $3,000 a Month in Spend?
Here is what these business credit card rewards look like on $3,000 a month, or $36,000 a year, in business spend. American Express Blue Business Cash’s flat 2% earns the most ongoing, about $720 a year, since the full amount falls under its $50,000 cap with no categories to track. Chase Ink Business Cash earns about $636 a year in a typical mix, assuming $500 a month on office supplies and internet, cable, and phone at 5% and $300 a month on gas and dining at 2%. Chase Ink Business Unlimited’s flat 1.5% earns about $540 a year.
The picture flips once you add the welcome bonus. Because both Chase Ink cards now carry a $1,000 bonus, Ink Business Cash actually tops first-year value at about $1,636, ahead of Ink Business Unlimited at about $1,540, while Blue Business Cash lands at about $970 on its smaller $250 bonus. So the best small business credit card on pure ongoing rate at this spend level is Blue Business Cash, but the best first-year value goes to Ink Business Cash.
| Card | Ongoing on $36,000/year | Year 1 with bonus |
|---|---|---|
| Chase Ink Business Unlimited | ~$540 (1.5%) | ~$1,540 |
| Amex Blue Business Cash | ~$720 (2%) | ~$970 |
| Chase Ink Business Cash | ~$636 (category mix) | ~$1,636 |
These figures assume your actual spend matches the categories used and stays within each cap, which real spending rarely does exactly, so treat them as a best-case illustration. Confirm each card’s live bonus and rate before you apply, since promotional offers on the best business credit cards for small business can change without notice.
How to Apply for a Business Credit Card
Once you’ve compared the best business credit cards for small business and chosen the best small business credit card for your needs, the application itself is usually straightforward. Cards like Chase Ink Business Unlimited and American Express Blue Business Cash can typically be applied for online in about 10 to 15 minutes, and sole proprietors can generally use a Social Security number instead of an EIN.
- Gather your business name, industry, an annual revenue estimate, and either an EIN or your SSN if you are a sole proprietor.
- Complete the online application, which is often approved instantly, though some need a few business days of manual review.
- If approved, activate the card on arrival and set up any employee cards you need.
- Set up autopay to avoid interest and stay in good standing for issuer credit-line reviews.
Choosing the Best Business Credit Card for Your Business
The single biggest factor is your annual spend level, and whether you want flat-rate simplicity or category-based rewards. Here is how the best business credit cards for small business sort out by situation:
- If you are a sole proprietor or freelancer with no LLC or EIN: Chase Ink Business Unlimited or American Express Blue Business Cash, both of which confirm an SSN works in place of a Tax ID.
- If you are a newer, lower-spend business that wants simplicity: Chase Ink Business Unlimited’s uncapped 1.5%, or Blue Business Cash’s 2% if your spend stays under $50,000 a year.
- If you are an established business with steady office, internet, phone, or dining spend: Chase Ink Business Cash’s 5% and 2% categories can out-earn either flat-rate card.
- If you are a high-spend business that can pay in full and wants the biggest bonus: Capital One Spark Cash Plus, though its $150 fee and Excellent-credit requirement make it the least accessible here.
- If you would rather earn flexible points than cash: American Express Blue Business Plus.
To qualify, you’ll need to be 18 or older with a US mailing address and a valid SSN or ITIN, sole proprietors can use their SSN instead of an EIN. Capital One Spark Cash Plus is the only one that states a credit tier, Excellent, the others fall in the good-to-excellent range.
None of these offer a business credit card no personal guarantee, so if that’s a dealbreaker, you’ll need a corporate card instead. For everyone else, start with the best business credit cards for small business that fit your spending, and use the bonus to decide between close calls.
Card needs also vary depending on the type of business you run, so explore our small business ideas guide if you’re still deciding what to launch.
How We Rate Business Credit Cards
We score every one of these best business credit cards for small business on four things, and fee-to-rewards value carries the most weight. The ranking is not arbitrary: we pull each fee, APR, and reward rate directly from the issuer’s own page, then weight the cards on the criteria below.
- Fee-to-rewards value (40%): what a low or $0 fee buys back in real, usable rewards.
- Fees and transparency (25%): APR range, any annual fee, and how clearly terms are disclosed.
- Eligibility (20%): how accessible the card is, including whether sole proprietors can apply with an SSN.
- Support and reviews (15%): issuer support and independent ratings.
We re-verify every fee, APR, and bonus quarterly, which matters most for Chase’s elevated $1,000 welcome bonus, a limited-time offer that can end without much notice.
Final Verdict
The Chase Ink Business Unlimited Credit Card takes the top spot among the best business credit cards for small business, thanks to its $0 fee, unlimited 1.5% cash back, $1,000 bonus, and NerdWallet’s 2026 award.
Still, American Express Blue Business Cash earns more if you spend under $100,000 a year, Chase Ink Business Cash rewards category spending best, Capital One Spark Cash Plus suits the highest spenders, and American Express Blue Business Plus is the pick for flexible points.
Every card here needs a personal guarantee, even for sole proprietors using an SSN, so confirm the current terms and choose based on your own business credit card rewards priorities.
FAQs
Chase Ink Business Unlimited ranks among the best business credit cards for small business, offering no annual fee, 1.5% cash back, and a $1,000 bonus. American Express Blue Business Cash is the higher-rate runner-up under $100,000 in annual spend.
On $36,000 a year in spend, these cards earn roughly $540 to $720 a year in ongoing business credit card rewards. With its $1,000 bonus, Chase Ink Business Cash tops first-year value at about $1,636. Figures depend on your spend matching each card’s categories.
No EIN is required. Sole proprietors and freelancers can apply for all five cards here using their own Social Security number in place of a business Tax ID, confirmed directly on Chase’s and Capital One’s own guidance pages. You still provide personal information and, in most cases, a personal guarantee.
It depends. Most require a personal guarantee and a hard inquiry at application, but ongoing balances usually report only to business bureaus. Issuers report to personal bureaus only if the account goes seriously delinquent, standard across the best business credit cards for small business.
Only Capital One states an exact tier, Excellent, for Spark Cash Plus. Aggregator consensus recommends good-to-excellent credit, roughly 670 or higher, for the other four best business credit cards for small business.