

Best Banks for Savings Accounts in 2026


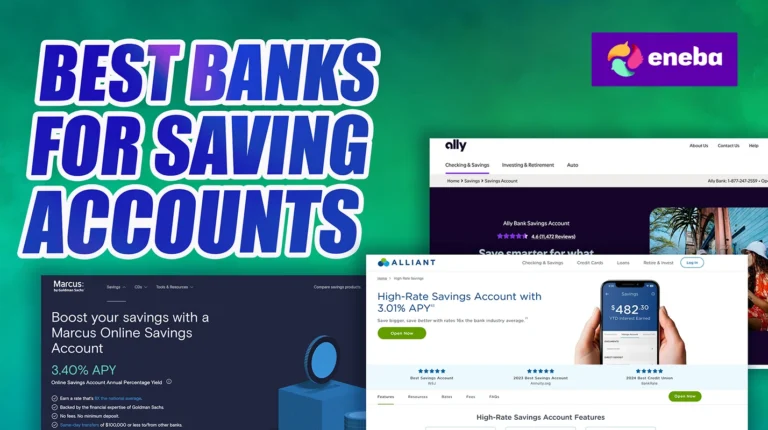
Marcus by Goldman Sachs tops our list of the best banks for savings accounts, with a verified 3.40% APY, no fees, and no minimum balance. That’s the highest rate among the five accounts we compare here, ahead of Alliant Credit Union (3.01% APY), Ally Bank, American Express, and Capital One (all 3.00% APY). Four of the five are banks; Alliant is a credit union that trades a slightly lower rate for member-owned perks the others don’t offer.
We built this best banks for savings accounts roundup from accounts open nationwide, paying an ongoing rate rather than a short-term promo, with a reasonable minimum deposit. That’s why you won’t see every account paying more than 3.40% here.
Every figure was confirmed directly on the provider’s page in August 2026, so think of this savings account comparison as a snapshot of the best savings accounts available right now, not a permanent ranking, and double-check the rate before you apply.
Jump to:
What Is a Savings Account?
A savings account is a deposit account that pays you interest for keeping money on deposit instead of spending it. Unlike a checking account, it isn’t built for everyday spending: most savings accounts limit how many withdrawals you can make each month and don’t come with a debit card for regular purchases.
The rate is quoted as APY, or annual percentage yield, which already factors in compounding, so it reflects what you actually earn in a year. A high-yield savings account simply pays a much higher APY than the national average, and four of the five best savings accounts on our list are online-first accounts built around exactly that trade-off.
A personal account like the ones here isn’t built to hold company money, either; for that, a business owner should look at one of the best business savings accounts for small business instead. Understanding that distinction is the real starting point for how to choose a savings account, since the highest rate only matters once you know what the account can and can’t do, and it’s the working definition we use throughout this best banks for savings accounts guide.
Best Banks for Savings Accounts: The Top 5 Compared
Here is how the top five stack up in our savings account comparison, covering the headline APY, the minimum balance needed to earn it, and what each account is best for, so you can shortlist in seconds and jump to the full review below. This table alone answers how to choose a savings account for most readers in under a minute, and it doubles as a quick best online savings account cheat sheet before you dig into the full breakdowns.
| Rank | Bank | Best For | APY | Minimum to Earn APY |
|---|---|---|---|---|
| 1 | Marcus by Goldman Sachs | Highest APY, zero fees | 3.40% | $0 |
| 2 | Alliant Credit Union | Credit-union perks, member ownership | 3.01% | $100 average daily balance |
| 3 | Ally Bank | All-around savings tools | 3.00% | $0 |
| 4 | American Express High Yield Savings | Existing Amex customers | 3.00% | $0 |
| 5 | Capital One 360 Performance Savings | Optional in-branch access | 3.00% | $0 |
None of these accounts advertises a cash sign-up bonus on the savings product itself, as of August 2026. Marcus occasionally runs a referral rate boost, an extra 1.00% APY for three months when an existing customer refers you, so check if it is live before you apply. That bonus wouldn’t change the ongoing savings account rates in the table above, so compare accounts on rate first, the same way you’d approach any best banks for savings accounts shortlist.
The Best Banks for Savings Accounts, Reviewed
Below is the full breakdown of each of the best banks for savings accounts on our list: the verified rate, the fees, the fine print, and who each account fits. The order runs from the highest rate down, and since Ally, American Express, and Capital One all pay the same 3.00% APY, we break that three-way tie using the rest of our weighted criteria: savings tools and independent ratings first, then how well the account fits an existing banking relationship, then physical branch access. Start with our top pick, Marcus by Goldman Sachs.
1. Marcus by Goldman Sachs: Best Overall
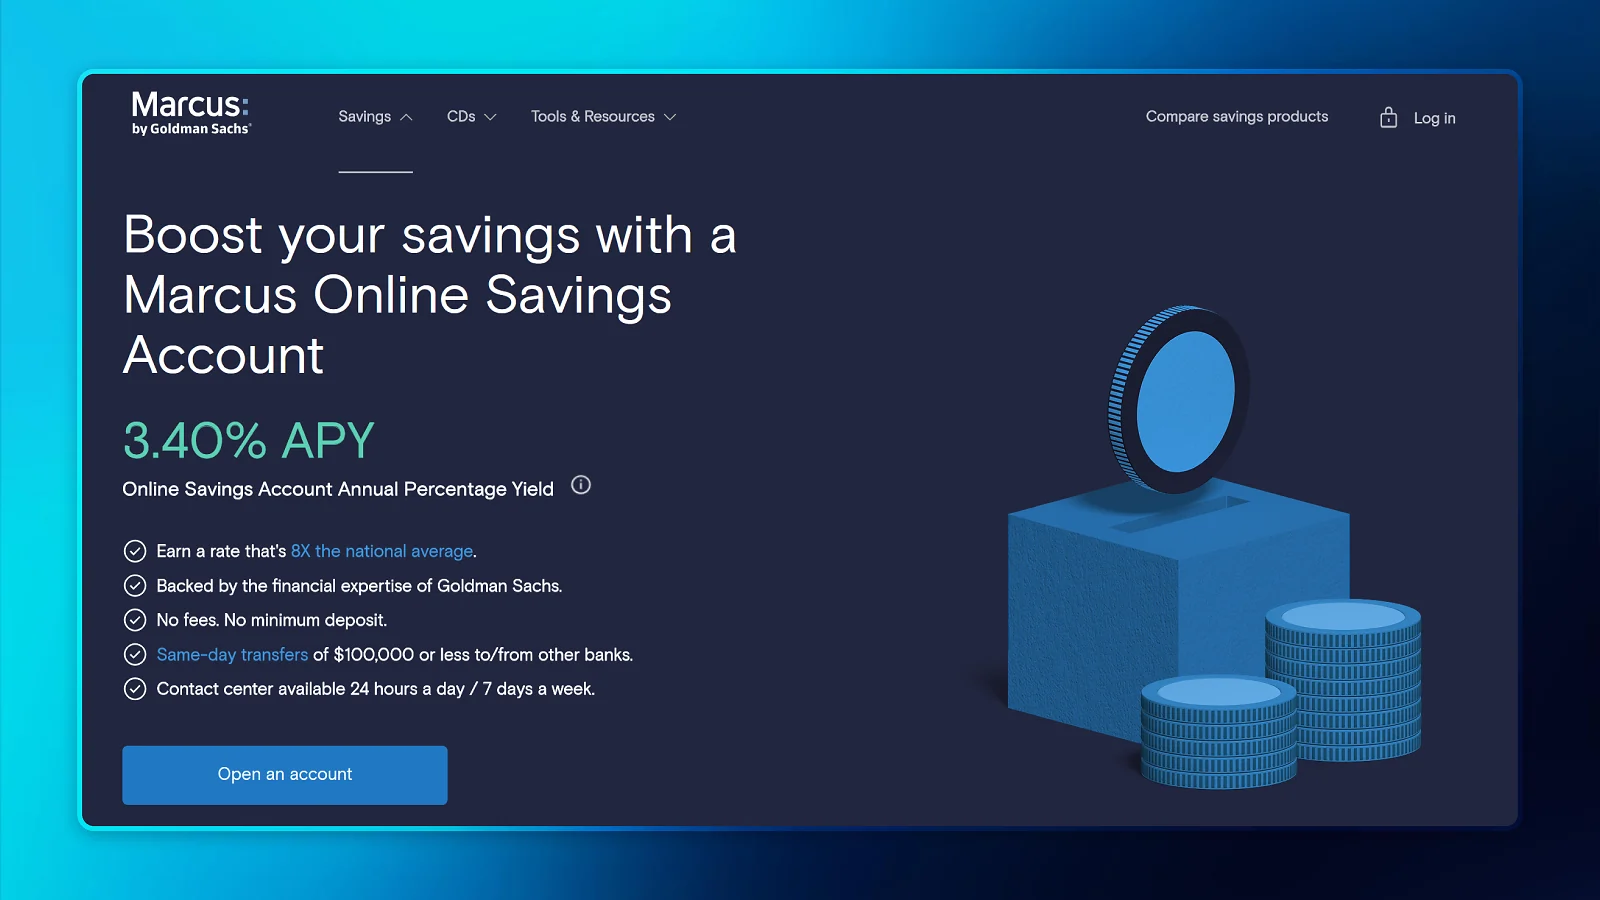
Marcus by Goldman Sachs is the best bank for a savings account overall, and one of the best high-yield savings accounts on the market, thanks to the highest verified rate in this comparison at 3.40% APY with no fees and no minimum balance.
| Account detail | Information |
|---|---|
| APY | 3.40% (confirmed on marcus.com, August 2026) |
| Monthly fee | $0 |
| Minimum to open / earn | $0 / $0 |
| Access | Online and app only, no branches |
| Insurance | FDIC (Goldman Sachs Bank USA, Salt Lake City Branch) |
| Best for | Savers who want the top rate with no balance rules |
The rate is the headline. At 3.40% APY, Marcus pays more than any other account on this list, and there is no minimum deposit, no minimum balance, and no monthly maintenance fee to chip away at your interest. Transfers to and from a linked external bank move same-day for amounts up to $100,000, and phone and chat support run 24/7.
Marcus also ranked #1 in Customer Satisfaction with High-Yield Savings Accounts from online-only banks in J.D. Power‘s 2026 study, per marcus.com. That kind of independent recognition is part of why it tops our list of the best savings accounts this cycle.
The trade-off is access: no branches, no ATM network, so this works better for parking cash than daily banking. Still, it’s a fair swap for the best online savings account rate in this group, and a clean best high-yield savings account done right: rate first, nothing extra. Providers adjust savings account rates often, so weigh this trade-off against the rest of this savings account comparison before you commit your cash.
Head to the savings account comparison below to see how Marcus stacks up against Alliant Credit Union.
2. Alliant Credit Union: Best Credit Union
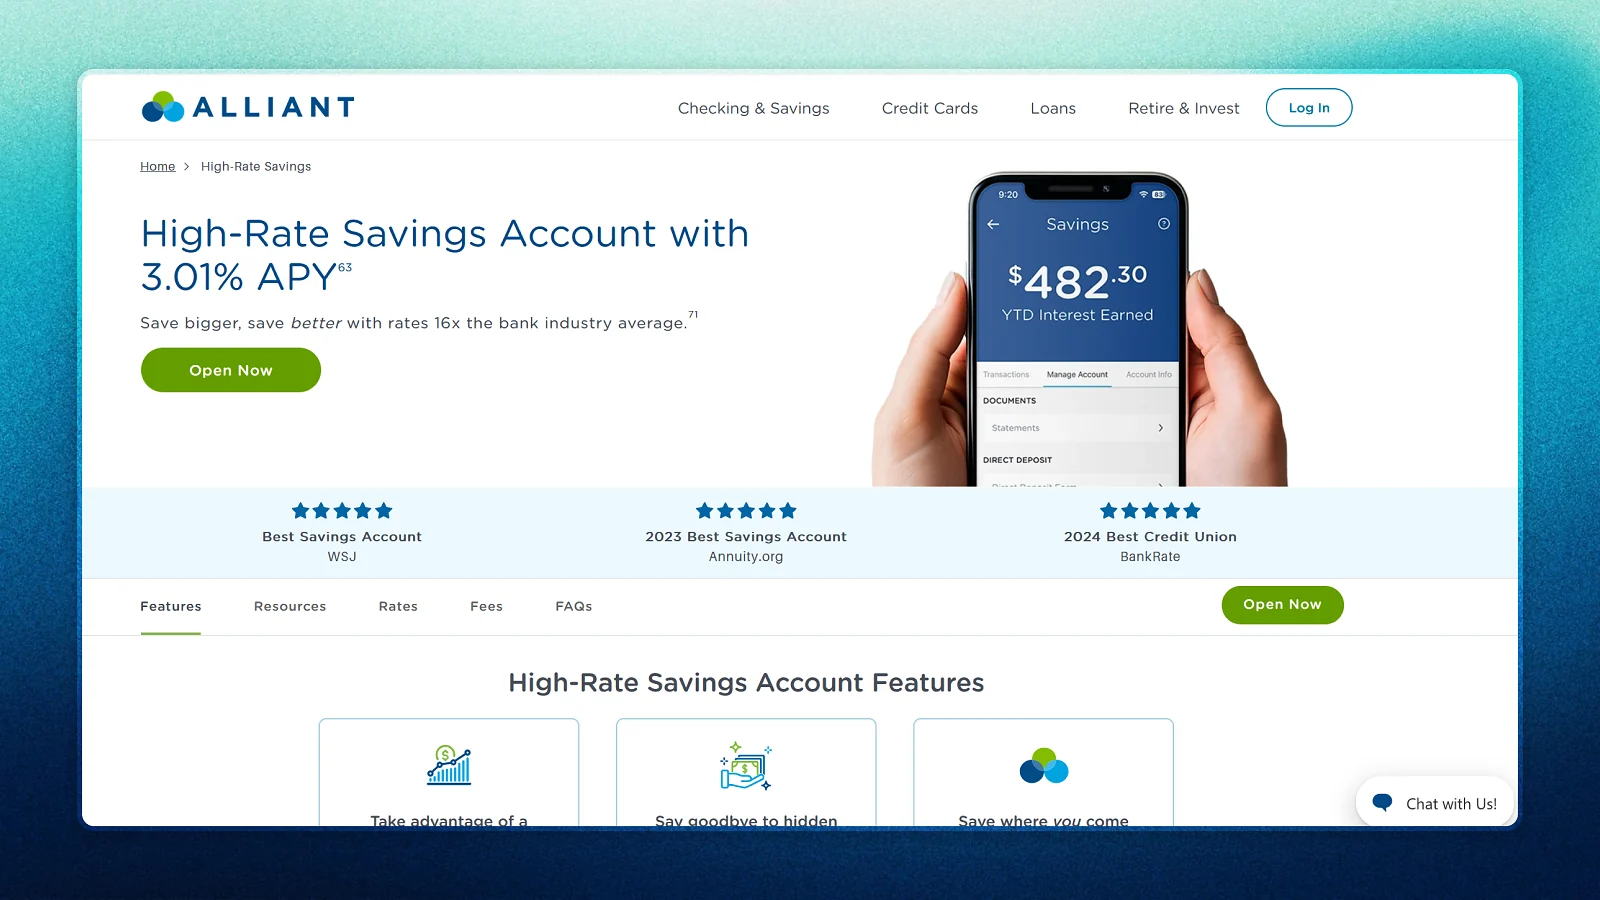
Among the best savings accounts on this list, Alliant Credit Union stands out for savers who want member-owned credit-union perks at a competitive rate: 3.01% APY (a 2.97% dividend rate) on balances of $100 or more.
| Account detail | Information |
|---|---|
| APY | 3.01% (2.97% dividend rate, as of August 7, 2026) |
| Monthly fee | $0 |
| Minimum to open / earn | $25 from you plus a complimentary $5 from Alliant ($30 total) to open / $100 average daily balance to earn |
| Access | Online and app, 80,000+ fee-free ATMs |
| Insurance | NCUA (not FDIC, Alliant is a credit union) |
| Best for | Perks like Early Payday and goal sub-accounts |
Alliant is the only credit union in this comparison, so deposits are insured by the NCUA rather than the FDIC. The rate is strong at 3.01% APY, and members get perks the banks here do not match: Early Payday deposits up to two days ahead, up to 19 free goal-based savings sub-accounts, and more than 80,000 fee-free ATMs. There’s even a same-rate kids savings account for members aged 12 and under, worth a look alongside our roundup of the best savings accounts for kids if you’re setting one up for a child.
Even without the top rate, this credit union is comfortably one of the best savings accounts for anyone who wants a member-owned institution. Perks like these are a big part of why it keeps a seat among the best banks for savings accounts despite a lower headline rate.
Before opening, keep two requirements in mind. You need a $100 average daily balance to earn the dividend, while the opening deposit is $30 total: $25 from you and $5 from Alliant. Membership can come through an employer, organization partner, or family member; otherwise, Alliant covers a $5 Foundation contribution.
These added steps may matter when choosing among the best banks for savings accounts. They’re also worth weighing against current savings account rates.
See the Alliant Credit Union vs. Marcus head-to-head below for a closer look at two of the best savings accounts.
3. Ally Bank: Best for Savings Tools
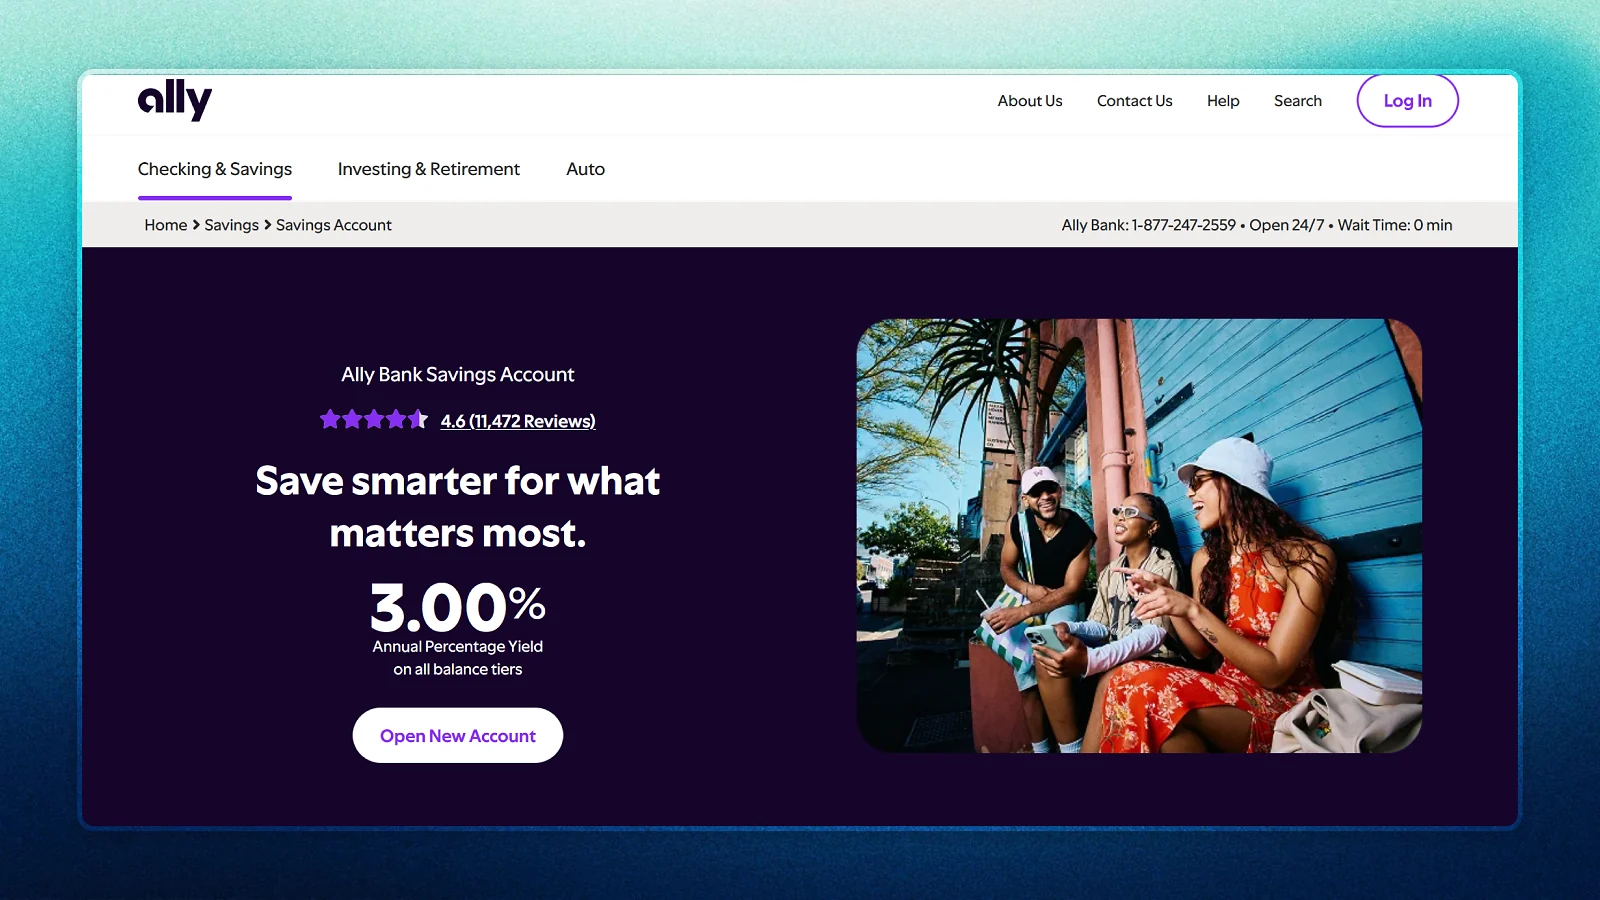
Ally Bank is the best fit for savers who want strong automation tools alongside a competitive rate, paying 3.00% APY on all balance tiers with no fees or minimums, one of three tied picks among the best banks for savings accounts we compare here.
| Account detail | Information |
|---|---|
| APY | 3.00% (confirmed on ally.com, August 21, 2026) |
| Monthly fee | $0 |
| Minimum to open / earn | $0 / $0 |
| Access | Online and app only |
| Insurance | FDIC |
| Best for | Automated savings tools (Buckets and Boosters) |
Ally matches the field at 3.00% APY, with no minimum deposit, no minimum balance, and no monthly maintenance fee. Where it stands out is the tools. “Buckets” let you split one account into separate savings goals, and “Boosters” automate the saving itself through recurring transfers, round-ups on spending, and a surprise-savings feature that moves spare cash from checking when your balance can spare it. Interest compounds daily.
Ally’s ratings tell a mixed story: Bankrate scores its savings account 4.4/5, while Trustpilot gives it just 1.4/5, largely due to customer-service and mobile-deposit complaints. There’s also a standard limit of 10 withdrawals per statement cycle.
Still, Ally earns its place among the best banks for savings accounts thanks to its strong automation tools. Those features also make it one of the best online savings account options for hands-off savers. Its savings account rates have fallen from 3.30% in January to 3.00% since June 3, so the current APY isn’t guaranteed to last.
4. American Express High Yield Savings: Best for Amex Customers
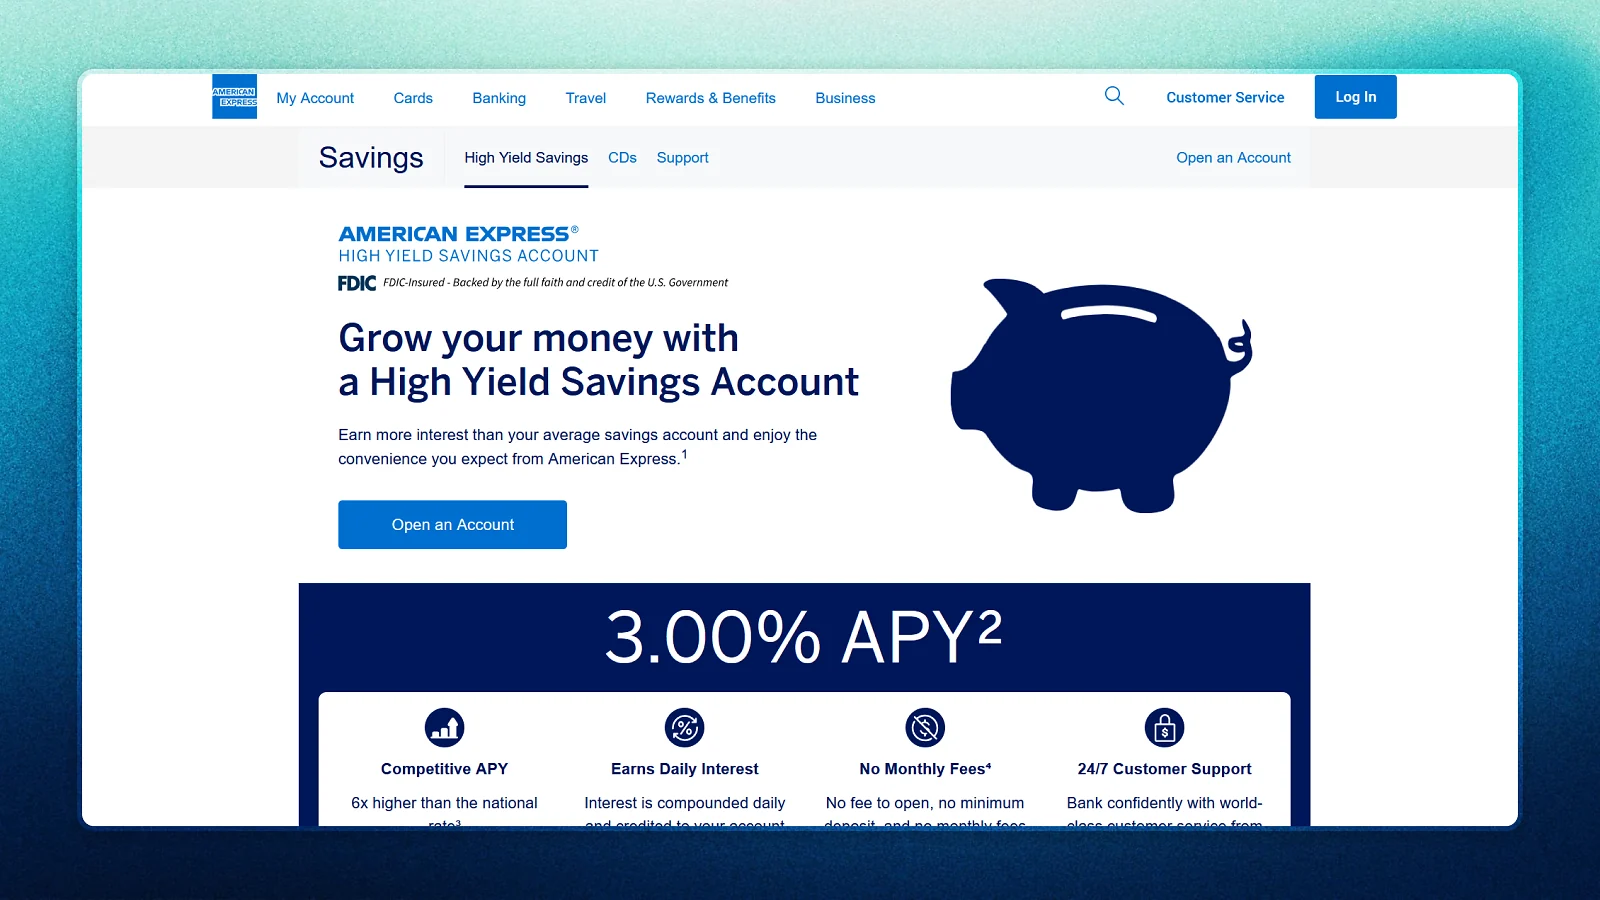
American Express High Yield Savings is the best choice for existing Amex cardholders who want one login for cards and banking, at 3.00% APY with no fees or minimum deposit, another of the three tied picks among the best banks for savings accounts on this list.
| Account detail | Information |
|---|---|
| APY | 3.00% (confirmed on americanexpress.com, August 24, 2026) |
| Monthly fee | $0 |
| Minimum to open / earn | $0 / $0 |
| Access | Online and app only |
| Insurance | FDIC (American Express National Bank) |
| Best for | Existing American Express customers |
If you already carry an American Express card, this account keeps everything under one login, which is the main reason to pick it over the near-identical online banks here. The rate is 3.00% APY with no minimum deposit and no monthly fees, interest compounds daily and is credited monthly, and support runs 24/7, still a solid best high-yield savings account pick even without Ally‘s extra tools. Deposits are FDIC insured through American Express National Bank.
It is a no-frills account. There are no branches, ATM access for savings, or goal-based tools like Ally offers. If you’re figuring out how to choose a savings account, the convenience of keeping your cards and savings under one Amex login may still be a deciding factor. That simplicity keeps it competitive, even if it ranks just behind Ally on features. It’s still one of the best online savings account options for existing Amex customers.
5. Capital One 360 Performance Savings: Best for Branch Access
For anyone weighing how to choose a savings account around in-person support, Capital One 360 Performance Savings is the pick: a 3.00% APY paired with access to Capital One branch and Cafe locations.
| Account detail | Information |
|---|---|
| APY | 3.00% (confirmed via independent rate trackers, August 2026) |
| Monthly fee | $0 |
| Minimum to open / earn | $0 / $0 |
| Access | Online, app, plus branches and Cafes |
| Insurance | FDIC (Capital One, N.A.) |
| Best for | Optional in-person branch access |
Capital One 360 Performance Savings is the only pick here with a physical footprint. You get a 3.00% APY with no minimum to open or maintain and no monthly fees, plus the option to walk into a Capital One branch or Cafe if you want face-to-face help. The mobile app is well reviewed, at 4.8 out of 5 on the App Store and 4.5 out of 5 on Google Play as of July 2026, both ranked in the top 10% of finance apps per capitalone.com. Those are app-store ratings, not a measure of savings-account satisfaction.
One wrinkle worth flagging: after Capital One acquired Discover‘s banking business, Discover‘s old Online Savings Account began directing users to Capital One 360 Performance Savings. Deposits are FDIC insured through Capital One, N.A. Branch access is what separates it from the other best online savings account picks here and explains its fifth-place finish in our tools-and-reviews tie-break.
Its savings account rates fell from 3.30% in early 2026 to 3.00%, so physical access is the stronger selling point. For some savers, that matters more when deciding how to choose a savings account.
Marcus by Goldman Sachs vs. Alliant Credit Union
Marcus and Alliant are the two highest-rate picks among the best banks for savings accounts on this list, which makes them the most useful head-to-head in this savings account comparison.
Marcus beats Alliant Credit Union for savers who want the single highest rate with zero balance requirements, mainly on APY (3.40% versus 3.01%) and a true $0 minimum to earn interest. Alliant still wins on member-owned perks like Early Payday and up to 19 free goal-based sub-accounts, so it’s the better pick if you want credit-union benefits and don’t mind keeping $100 in the account, which is really how to choose a savings account between these two.
Deposit protection is a wash: Marcus is FDIC insured, Alliant is NCUA insured, and both cover $250,000 per depositor. That single gap is the clearest data point in this savings account comparison between the two highest-rate picks here.
| Feature | Marcus by Goldman Sachs | Alliant Credit Union |
|---|---|---|
| APY | 3.40% | 3.01% (2.97% dividend rate) |
| Minimum to earn | $0 | $100 average daily balance |
| Monthly fee | $0 | $0 |
| Membership | None required | Credit-union membership required |
| Standout perk | Highest rate, same-day transfers | Early Payday, 19 goal sub-accounts |
| Insurance | FDIC | NCUA |
Pick Alliant instead if the credit-union perks and the kids savings option matter more to you than squeezing out the last 0.39% of yield. Either way, both remain two of the best banks for savings accounts on this list, and solid answers to how to choose a savings account when credit-union membership is or isn’t a priority for you.
Editor’s Pick
Editor’s Pick: Marcus by Goldman Sachs. Our top pick among the best banks for savings accounts this cycle, chosen for the highest verified APY in this set at 3.40%, with zero fees and no minimum balance to open or earn interest. It’s the simplest way to earn the top rate in this comparison and a strong contender for the best online savings account overall, since the lack of minimums means every dollar starts working right away.
Skip it if you want in-branch banking or credit-union perks like Early Payday, where Alliant Credit Union is the better fit. Either pick keeps you inside the best high-yield savings account tier we verified this cycle, so you give up little on rate either way, no matter which of the best banks for savings accounts here you choose.
How Much Can You Earn With a Savings Account?
Here’s what the top rate among the best banks for savings accounts looks like in real numbers. $5,000 in Marcus‘s account at 3.40% APY earns about $170 in a year. Put in $25,000 and that grows to roughly $850, assuming the rate holds for the full 12 months.
The table below scales the example across three balances. These numbers shift whenever savings account rates move, so treat them as a snapshot rather than a promise.
| Starting balance | Approx. earned in 1 year at 3.40% APY |
|---|---|
| $1,000 | ~$34 |
| $5,000 | ~$170 |
| $25,000 | ~$850 |
These are simple, illustrative estimates at a flat 3.40% APY with no withdrawals. APY already reflects the effect of compounding, so this figure isn’t something daily compounding would push any higher.
The rate is variable and confirmed only as of August 2026, so your actual return depends on the APY at the time and how long your balance stays put. That’s exactly why we rebuild this savings account comparison every quarter, checking every one of the best savings accounts here instead of leaving old numbers in place.
How to Open a Savings Account
Opening the best online savings account, like Marcus‘s, typically takes about 5 to 10 minutes. None of these five run a hard credit check the way a credit card issuer would, but most banks screen new deposit accounts through ChexSystems or a similar consumer-reporting service that looks at your banking history rather than your credit score.
The process is nearly identical at every best online savings account provider on this list, so the steps below apply across the board, and opening a second account later in this best banks for savings accounts roundup takes even less time.
- Complete the online application with basic ID and your SSN or ITIN.
- Verify your identity, which is often instant but can take 1 to 2 business days.
- Fund the account by bank transfer, mobile check deposit, or wire.
- Start earning interest as soon as the funding transfer posts.
Choosing the Best Savings Account for You
Knowing how to choose a savings account starts with comparing the APY you can realistically earn, but features and banking access matter too. The bullets below map each persona straight to one of the best banks for savings accounts on our list.
- If you want the highest rate with no strings: go with Marcus by Goldman Sachs, at 3.40% APY and $0 minimum to open or earn.
- If you prefer a member-owned credit union and can keep $100 in the account: Alliant Credit Union is the better match.
- If you want in-person help alongside an online rate: Capital One 360 Performance Savings has branch and Cafe access.
- If you already bank with Ally or Amex and want one login: Ally Bank or American Express High Yield Savings keep everything together.
Minimum eligibility is similar across the board: you must be 18 or older with a valid SSN or ITIN, and, for four of the five, a US mailing address. Alliant is the exception on residency: it states that applicants living outside the US can still join with a Social Security number or a valid ITIN.
Alliant also adds one step the other four skip, credit-union membership at sign-up, and none of the five run a hard credit check, though most screen new accounts through ChexSystems rather than a credit score.
That’s really how to choose a savings account: match the account to how you bank, then compare the rate among the best banks for savings accounts you’re considering.
If your priority is everyday spending rewards rather than parking cash, weigh these picks against the best credit cards for cashback instead. Every option above remains one of the best savings accounts worth comparing before you open anything.
How We Rate Savings Accounts
We score every one of the best banks for savings accounts on four things, and rate value carries the most weight. The ranking isn’t arbitrary in this savings account comparison: we pull each figure from the provider’s official page, then weight the accounts on the criteria below.
- Rate value (40%): the APY you actually earn, after any balance requirement.
- Fees and transparency (25%): monthly, transfer, and overdraft fees, and how clearly they are disclosed.
- Eligibility (20%): how easy the account is to open and who qualifies, a factor that matters most when weighing the best savings accounts for your situation.
- Support and reviews (15%): customer support options and independent ratings like Trustpilot.
When two or more accounts tie on rate, we work down this list in order, fees, then eligibility, then support and reviews, to break the tie. That’s exactly how Ally, American Express, and Capital One sort into third, fourth, and fifth place despite sharing the same 3.00% APY.
We re-verify rates and refresh this ranking quarterly, and because savings account rates are variable, we recheck the winner’s APY before every update. That same discipline is what keeps our best high-yield savings account picks trustworthy quarter after quarter.
Final Verdict
For most savers, Marcus by Goldman Sachs is the standout among the best banks for savings accounts we compared this cycle. It pays the highest verified rate in this comparison at 3.40% APY, charges no fees, and asks for no minimum balance, so every dollar earns from day one. Alliant Credit Union is the runner-up and the pick if you want credit-union perks and a kids savings option, while Ally, American Express, and Capital One are all solid 3.00% choices that make more sense if you already bank with them or want in-person access.
Whichever route you take, confirm the live APY on the provider’s page first, since rates move. Ready to earn more on your cash? Open your account and start earning today’s rate.
FAQs
Marcus by Goldman Sachs is the best bank for a savings account right now, at 3.40% APY, the highest of the five accounts we compared as of August 2026. Alliant Credit Union is the runner-up if you’d rather bank with a credit union.
At the top rate of 3.40% APY, $5,000 earns about $170 over a year and $25,000 earns roughly $850. The rate is variable, so run the same math against any of the best banks for savings accounts you’re weighing, not just the top pick here.
Yes. Every one of the best banks for savings accounts on our list carries deposit insurance up to $250,000 per depositor: Alliant through the NCUA, and Marcus, Ally, American Express, and Capital One through the FDIC.
No credit score is required, unlike a credit card. Most banks instead screen applicants through ChexSystems or a similar service that looks at your banking history, not your credit. You’ll need a valid ID, an SSN or ITIN, and to be 18 or older, or a custodial setup for a minor.
Yes, through a custodial or joint account with a parent or guardian as co-owner. Alliant offers a same-rate kids savings account for members 12 and under, one reason these rank among the best banks for savings accounts for families.
Marcus by Goldman Sachs, with a verified 3.40% APY, well above the roughly 0.38% national average. If credit-union perks matter more to you than the single highest rate, Alliant Credit Union wins this savings account comparison on perks instead.